
Introduction
Freelancing gives you freedom, but income may change monthly. You might earn ₹70,000 one month and ₹25,000 the next, while bills stay the same.
A 2026 Federal Reserve report found that 58% of self-employed US adults experienced month-to-month income variation, compared with 28% of employees. An August 2026 Experian survey found that more than 80% of 503 US gig workers experienced unpredictable income. These US findings show why a freelance money plan matters.
Learning how to manage money with irregular income can help you cover essentials, prepare for taxes, and avoid depending on your next client payment. A simple plan also helps you prepare for both busy and quiet months. A routine shows how to manage money in lean months.
Why Money Management Is Different for Freelancers
Freelancers are paid by project or invoice. Remember: revenue is client money received, business profit is what remains after work costs, and take-home income is what is available after business costs and tax reserves. A client payment is not automatically spendable money.
7 Practical Ways to Manage Money as a Freelancer
1. Calculate Your Average and Lowest Monthly Income
Review client payments over 6–12 months and subtract business expenses to understand your earnings before personal taxes. This is the first step in deciding how to manage money safely. Use this history to plan for slower periods.
| Month | Client payments |
|---|---|
| January | ₹55,000 |
| February | ₹35,000 |
| March | ₹65,000 |
| April | ₹28,000 |
| May | ₹50,000 |
| June | ₹42,000 |
Your average receipts are about ₹45,833, but this is not personal income. Use earnings after business expenses and a conservative figure for essential spending. If essentials cost ₹25,000 and income often falls below ₹30,000 before business costs and taxes, reduce flexible spending and review your figures every three months.
2. Separate Business and Personal Finances
Keep business and personal accounts separate where possible. Otherwise, track client receipts and work costs clearly.
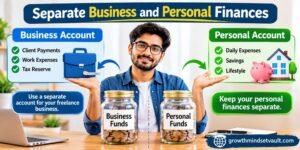
Track client payments and work costs, then transfer a planned amount to your account. This freelance money management habit simplifies records. It is one way to learn how to manage money across business and personal needs.
3. Build a Budget Around Essential Expenses
Base your budget on necessary spending, not your best earning month. Freelance budgeting matters.
| Expense type | Examples |
|---|---|
| Essential | Rent, groceries, electricity, transport |
| Work-related | Internet, software, equipment |
| Flexible | Shopping, dining out, entertainment |
If personal essentials are ₹25,000 and business costs are ₹5,000, your basic freelance budget is ₹30,000 before taxes and savings. If income after business costs falls below this, reduce flexible spending and follow up on unpaid invoices. This shows how to manage money without relying on peak earnings. Save high-month surpluses for future bills.
4. Pay Yourself a Consistent Monthly Income
To manage money as a freelancer, set a regular personal transfer date. This simple freelancer budgeting routine creates consistency. It is a useful practice in money management for freelancers. Keep client payments in a holding account instead of spending them immediately.
For each payment, record it, cover business costs, reserve estimated taxes, add to savings, and transfer your planned pay.
For example, from ₹60,000, an illustrative allocation might be ₹8,000 for business costs, ₹10,000 for estimated taxes, and ₹5,000 for a buffer. The remaining ₹37,000 can support personal pay and other savings. These are examples, not universal percentages.
Choose a transfer date to prevent overspending. A simple freelancer money plan reduces uncertainty and shows how to manage money after each client payment.
5. Set Aside Money for Taxes
Knowing how to manage money also means planning for taxes. Freelancers must plan for taxes. Your reserve depends on local rules and your tax situation. Estimate your liability rather than copying another freelancer.
For freelancers in India: For financial years beginning on or after 1 April 2026, Section 404 of the Income-tax Act, 2025 provides for advance tax when tax payable under the applicable provisions is ₹10,000 or more, subject to the Act’s conditions. Earlier financial years were governed by the Income-tax Act, 1961. Check the rules for the relevant year or speak with a qualified tax professional.
If a client deducts tax at source (TDS), record it and check the tax credit. TDS is not automatically your final liability. Keep tax money separate from everyday spending.
6. Build a Cash-Flow Buffer and an Emergency Fund
These savings have different purposes. Knowing how to manage money also means preparing for both delayed payments and unexpected costs.
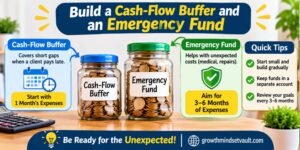
- Cash-flow buffer: Covers short gaps when a client pays late or a project is postponed.
- Emergency fund: Helps with unexpected events such as medical costs, equipment failure, or a longer loss of income.
Start with a one-month cash-flow buffer, then work towards an emergency fund covering three to six months of essential personal and business costs. You may need more if you have dependants or few clients.
If essentials cost ₹25,000 monthly, three months equals ₹75,000. This is an example, not a universal target; keep it accessible. This reserve helps you manage money when work slows unexpectedly.
7. Prepare for Slow Months and Late Client Payments
Prepare before income falls; this is part of learning how to manage money during quiet periods. Atradius’s 2025 India Payment Practices Barometer reported overdue invoices among surveyed B2B businesses. Although not freelancer-specific, it is a reminder that unpaid invoices are not cash in hand.
Protect freelance income with advances, milestone payments, clear due dates, prompt invoices, and polite follow-ups. Track freelance cash flow weekly, review your client mix, and record each invoice’s amount, due date, and status.
Common Money Management Mistakes Freelancers Should Avoid
- Spending every payment: Client receipts are not all disposable income.
- Ignoring unpaid invoices: Count money only after it arrives.
- Waiting to save: Start with an affordable amount from each payment.
- Depending on one client: Gradually build a more balanced client base.
Frequently Asked Questions
How should freelancers budget with irregular income?
Review 6–12 months of income, subtract business costs, and budget essentials using a conservative estimate. This is a useful freelancer budgeting habit. Keep surplus for slower months. This is a reliable way to learn how to manage money.
How much should freelancers save each month?
First cover business costs and estimated taxes, then save an affordable amount. Reduce the target in low-income months. This is how to manage money without forcing an unrealistic budget.
Should freelancers separate business and personal money?
Yes. Separate accounts or clear records help track payments, costs, personal spending, and tax reserves.
Conclusion
To manage money as a freelancer, keep your plan consistent even when income changes. Track payments, budget essentials, pay yourself regularly, and reserve taxes.
Give each client payment a purpose before spending it. That simple habit can help you manage money with more confidence. Start by calculating essential monthly costs and reviewing six months of income. This is a practical first move when deciding how to manage money.
Want to build better money habits and make smarter financial decisions? Visit GrowthMindset Vault for practical guides that help you take control of your finances and your future.
Disclaimer: Financial and tax rules vary by location and individual circumstances. Check current official guidance before making tax decisions.